September 17, 2026

It’s the question buyers have been asking for years: Should you buy a home now, or wait for mortgage rates to fall? With rising interest rates, it’s easy to understand why.
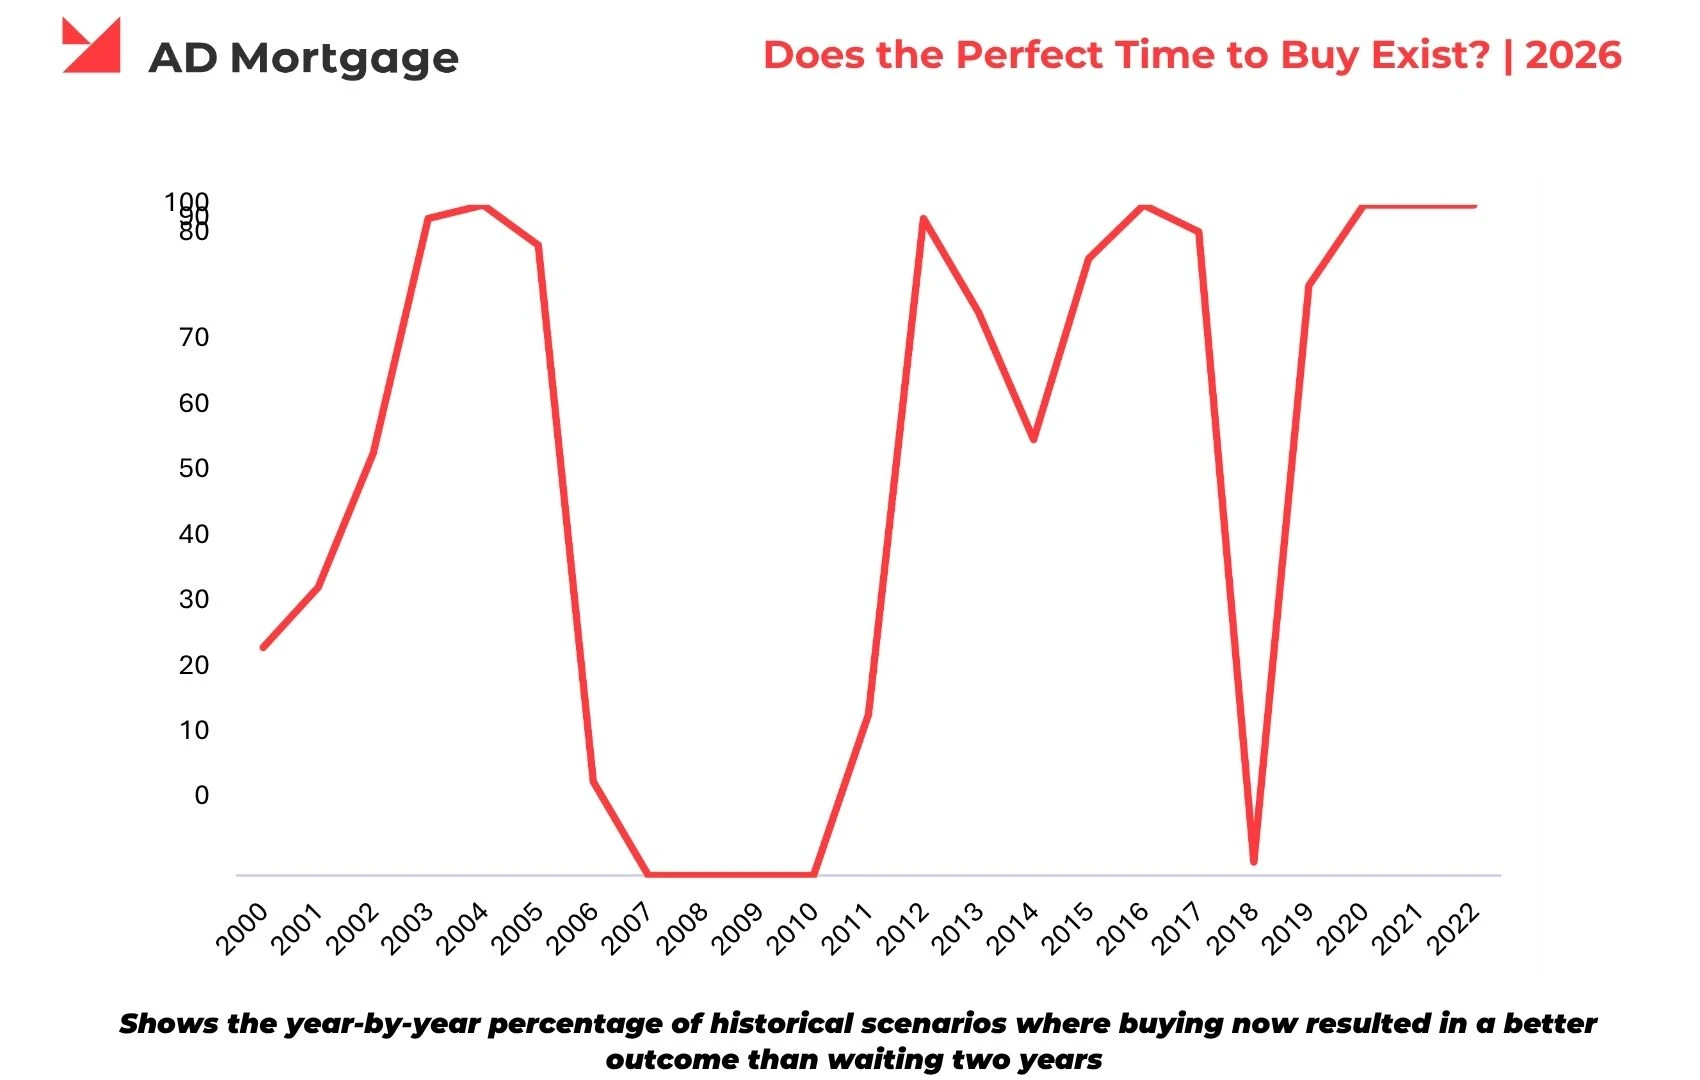
A new study from AD Mortgage looked at more than 20 years of housing data and found that buying immediately produced a better financial outcome than waiting two years in 61% of the scenarios studied.
This doesn’t mean buyers should go out and purchase immediately; it simply means that timing the market is more challenging than it looks.
Lower Mortgage Rates Don’t Always Mean a Better Deal
When looking at interest rates over 6%, it makes sense that so many buyers think waiting sounds simple. Hold off for a year or two, and you can save money and hope interest rates drop, and then purchase when conditions are better.
However, we see problems arise because many things can change while you’re waiting.
AD Mortgage compared what actually happened between 2000 and 2022. Its calculations considered home prices, 30-year mortgage rates, household income, and the additional savings a household could build by waiting two years.
The results show why focusing on mortgage rates alone can be misleading.
Take 2013. The average 30-year mortgage rate was 3.98%. By 2015, it had fallen slightly to 3.85%.
You might assume waiting would have paid off, but it usually didn’t.
Buying in 2013 produced the better financial outcome in 84% of the state scenarios studied. Changes in home prices and other costs outweighed the benefit of the lower rate in many places.
Sometimes Waiting Really Is Better
That doesn’t mean buying now is always the answer. In fact, it’s far from it.
During the housing and financial crises, waiting was clearly the better move. From 2007 through 2010, buying immediately failed to produce the better financial outcome in any of the state scenarios.
This is an important part of the study. While housing markets change, so do people’s finances. A buyer who has stable income, savings, and plans to stay in their home for years is in a drastically different position from someone facing job uncertainty or struggling to afford the monthly payment.
Instead of waiting for the market to send a perfect signal, the study suggests buyers focus on whether they’re financially ready to buy.
What Does This Mean for Home Sellers?
There’s another side to this story. Buyers trying to time the market affect sellers, too.
When buyers worry about rates, home prices, or the economy, they may take longer to decide. They can also be more careful about what they’re willing to pay and which homes they’re willing to consider.
For sellers, that can mean more uncertainty.
We’ve worked with homeowners who thought their sale was finished, only to have a buyer back out before closing. One homeowner in Woodbridge, Virginia, had already planned his move when his original deal fell apart at the last minute. House Buyers of America purchased the home As-Is and closed in 30 days, allowing him to stay on schedule.
It’s a good reminder that accepting an offer isn’t always the finish line.
Sellers Can’t Always Wait for the Perfect Market Either
The same lesson applies to homeowners considering a sale.
It’s tempting to wait for home prices to rise, mortgage rates to fall, or buyer demand to improve. Sometimes waiting works.
Sometimes life doesn’t give you that option.
A job relocation may come with a firm start date. An inherited home can continue adding taxes, insurance, and maintenance costs while it sits vacant. Retirees may be ready to downsize, while other homeowners simply don’t want to spend months repairing and preparing a house for sale.
Your Situation Matters More Than the Headlines
For buyers and sellers alike, there’s no single date when the housing market suddenly becomes perfect.
AD Mortgage’s findings show how much results have changed by year and location. The study also cautions that its findings are based on historical data and aren’t a prediction of what will happen next.
That’s worth remembering.
If you’re selling a move-in-ready home, have plenty of time, and want to pursue the highest possible sale price, a traditional listing may make the most sense.
But not every homeowner is in that position.
Whatever situation you find yourself in, House Buyers of America offers another path. Since 2001, we’ve helped homeowners sell houses As-Is when a traditional sale wasn’t the right fit. We make competitive cash offers, pay all normal closing costs, and never ask sellers to make repairs before closing.
The housing market will always change.
Waiting for the perfect moment may mean waiting for something that never comes. What’s more important is choosing the time and selling option that make sense for your home, your finances, and your life.

Recent Posts


Frequently Asked Questions (FAQs) About Selling Your Home Fast
During a transfer, a new deed is drafted and signed by the seller, transferring ownership of the house to the new buyer. This document is then recorded in the land records with the above-mentioned deed of trust.
We work with your bankruptcy attorney to present a FAIR offer and give you additional money at closing. We present the offer directly to your attorney and work to have the offer accepted by the bankruptcy court. Once the offer is accepted, we ensure that the bankruptcy is released and we buy the property as soon as possible.
Yes, we can work with any seller who needs to move a property quickly for any reason and in any price range. We have purchased million-dollar houses before.
Yes, we buy apartments, multi-family houses/buildings and land.
No! You have no obligation at all if you submit an information form, show your property to House Buyers or receive an offer to buy your house. You are under no obligation at all. All we ask for is the opportunity to make an offer for your house, you’re in the driver’s seat as to whether you accept the offer or not. You are in complete control. You are only obligated to our service if you have entered into a purchase agreement with us, as with any other real estate transaction.
We need very basic information from you about your house. The number of bedrooms, bathrooms and overall condition of the property is needed. We will also ask you how long you have owned your home and if there are any mortgages or liens against the property.
We offer the maximum amount possible, our offers are very competitive. If our offers weren’t competitive, we wouldn’t have purchased thousands of houses! There is no magic percentage we use, every house is unique. Our Real Estate Consultants take into consideration the age, condition, size, features and location of the home much like an appraiser would. We factor in the costs to repair the house, what other homes in the area are selling for and how long it is taking to sell those homes. These and several other factors are researched to determine a fair offer.
As soon as we receive your Online Form, we will review your information and get back to you ASAP (usually within 30-60 minutes depending on when you submit the information).
We work FAST to help ensure that your house doesn’t go to foreclosure. We present you with a FAIR offer to pay off your mortgage before the foreclosure. We help save your credit, avoid foreclosure and allow you to sell your house FAST and FAIR. Due to recent legislation, if you reside in the state of Maryland and are within a certain period of time before your foreclosure sale date, we will introduce you to a Foreclosure Consultant. The legislation mandates that if you are within this certain window that a foreclosure consultant must explain to you all of your options involved in selling your home.
No problem! We can still buy your house as is, even if it has demolition orders scheduled.
House Buyers of America
We buy your home on your terms.
- No repairs or showings
- Close on your time frame
- No commissions or fees
- No obligation cash offer
Over 25 Years in Business · Trusted Since 2001
Get Your Fair Cash
Offer
Today!
or call us at 855-659-3289
Searching and Processing Address